AI Investment in 2026: From Chip Hoarding to Energy Hunger
The AI funding landscape has shifted. Hyperscalers spent $200B on infrastructure, but the real money is now flowing into energy, custom ASICs, and agentic workflows. Here's what the data shows.
The AI investment story in 2026 is not the same story as 2024. Two years ago, the question was whether AI would live up to the hype. Today, the question is where the next wave of returns will come from, now that the initial infrastructure buildout is maturing.
The numbers tell a clear story. According to AlphaSense research, over 16,000 AI-related deals closed across 2025 and 2026. But the distribution of that capital has changed dramatically. The money is no longer flowing broadly across every AI startup with a pitch deck. It is concentrating into specific channels, and understanding those channels matters if you want to know where the industry is heading.
The $200 billion question
Microsoft, Google, Amazon, and Meta collectively allocated over $200 billion toward AI infrastructure in 2026. That number is staggering on its own, but the more interesting question is what happens next.
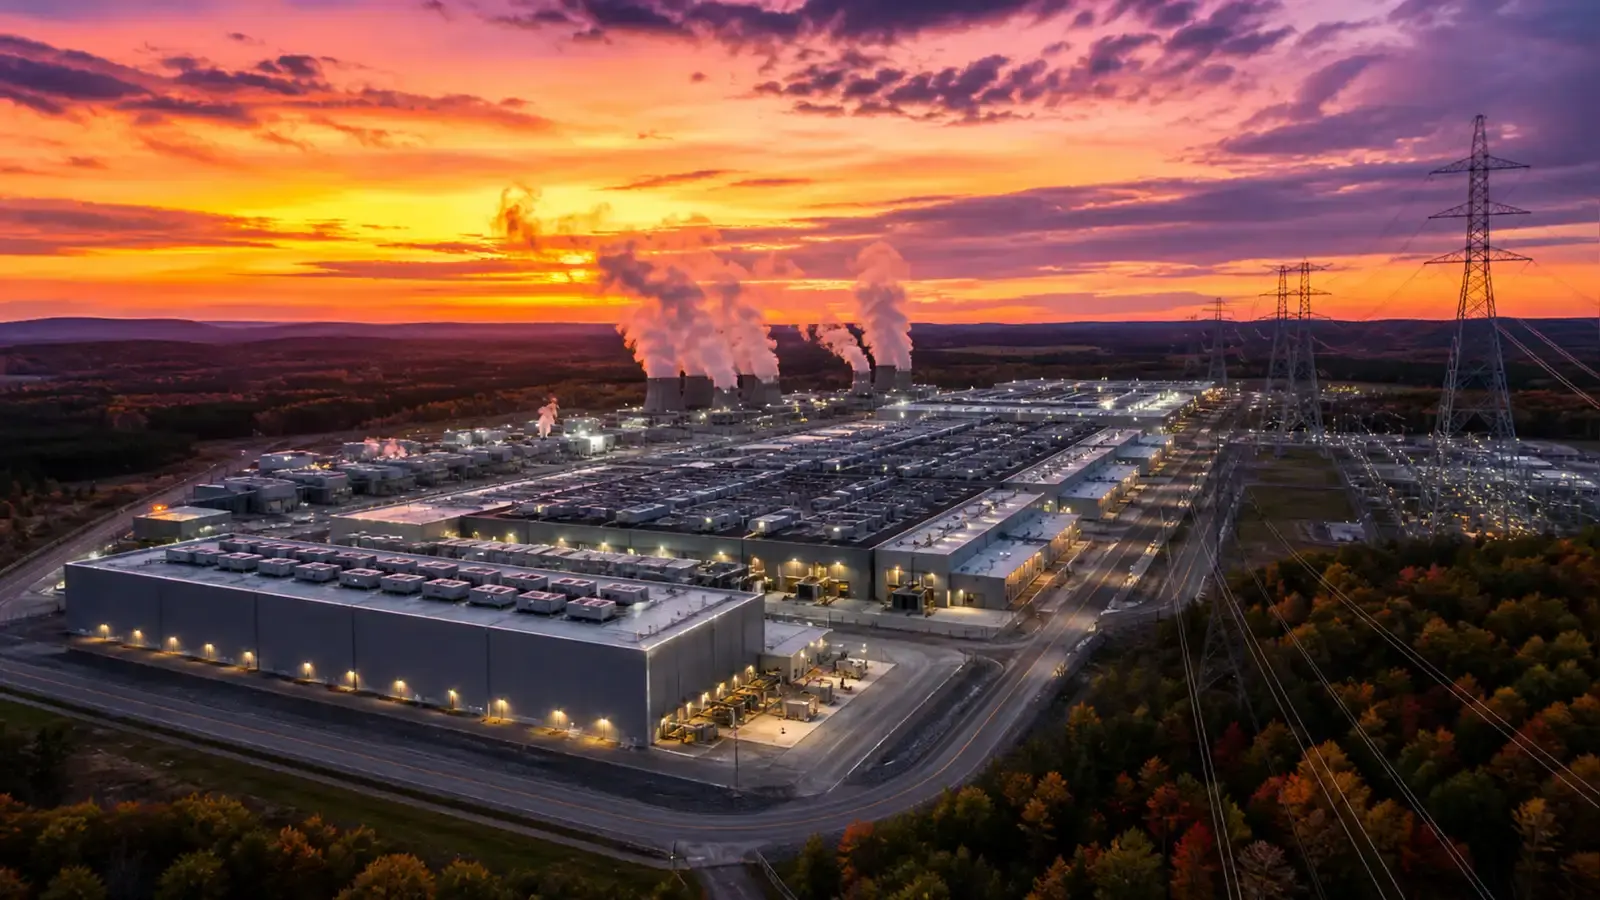
The chip-buying boom is winding down. Not because companies have enough compute, but because the bottleneck has shifted. GPUs are available. The problem is powering them. Data centers consume enormous amounts of electricity, and the grid is not keeping up. This is why energy has become the new frontier of AI investment. The numbers are sobering. A single large training cluster can consume as much electricity as a small city. When you multiply that across the thousands of data centers being built worldwide, the demand on power grids becomes impossible to ignore. Several utility companies have reported that AI-related demand now accounts for more than 15% of their total load growth, a figure that was near zero just three years ago.
The investment implications are concrete. Companies like NextEra Energy and Brookfield Renewable have seen their AI-related power contracts grow exponentially. Data center operators are signing long-term power purchase agreements that lock in electricity prices for a decade or more, essentially treating energy as a raw material input on par with silicon and networking equipment.
Investors are noticing. Capital is flowing into AI-driven energy systems, power procurement deals, and infrastructure that can support the next generation of model training. The focus has moved from “can we build the chips” to “can we keep the lights on.”
The geographic distribution of this investment is also shifting. Northern Europe, with its abundant hydroelectric and wind power, is becoming a magnet for data center construction. Iceland and Norway are seeing unprecedented interest from AI companies looking for cool climates (reducing cooling costs) and clean energy. Meanwhile, in the United States, states like Texas and Georgia are competing for data center jobs by offering tax incentives and fast-tracked permitting for power infrastructure.
This geographic shift has geopolitical implications. Countries that control energy infrastructure for AI will have leverage in the same way that oil-producing nations had leverage in the 20th century. The difference is that AI energy demand is more distributed and harder to embargo, which may actually make the market more stable but also more complex.
Where the big rounds went
The largest funding rounds of 2026 reveal where smart money is placing its bets:
- Prometheus raised $12 billion in a Series B at a $41 billion valuation, making it the largest AI funding round of the year. The company works on foundational AI and machine learning infrastructure.
- DeepSeek secured $7.4 billion in a Series A at a $50 billion valuation. The Chinese AI lab has gained attention for its efficient model architecture and aggressive pricing on developer APIs.
- Isomorphic Labs raised $2.1 billion in a Series B at $5.45 billion, focusing on AI applications in life sciences and drug discovery. This is one of the clearest signals that AI investment is expanding beyond pure tech into adjacent industries.
On the infrastructure side, Fluidstack raised $830 million at a $7.5 billion valuation for GPU cloud infrastructure, while MatX pulled in $500 million at $1 billion for custom AI ASICs. Both reflect the growing recognition that off-the-shelf hardware is not always the most efficient path. The MatX investment is particularly telling. Custom ASICs for AI inference have been discussed for years, but 2026 is the year the economics finally work. When you are running millions of inference calls per day, the difference between a general-purpose GPU and a purpose-built chip can translate to tens of millions in annual savings. Investors are betting that this cost advantage will only widen as model architectures stabilize.
The DeepSeek round deserves attention for a different reason. A Chinese AI lab raising $7.4 billion at a $50 billion valuation signals that the AI race is not just an American story. DeepSeek’s approach to model efficiency, using less compute to achieve comparable results, challenges the assumption that more hardware always equals better performance. If their approach proves scalable, it could reshape how the entire industry thinks about infrastructure spending.
The robotics sector also attracted significant capital. Apptronik raised $520 million at a $5.5 billion valuation for industrial automation. Rhoda AI pulled in $450 million at $1.7 billion for foundational AI applied to robotics. These investments reflect a growing belief that the next frontier for AI is not just software but the physical world. Robots that can navigate unpredictable environments, handle fragile objects, and work alongside humans require both advanced AI models and sophisticated hardware, and investors are betting that the integration of these two domains will create enormous value.
The life sciences angle is equally compelling. Isomorphic Labs, backed by DeepMind’s founders, is using AI to accelerate drug discovery. The premise is simple: if AI can predict protein structures (as AlphaFold demonstrated), it can also predict which molecules will be effective drugs. The $2.1 billion bet suggests that investors believe this is not just possible but likely, and that the payoff could be measured in hundreds of billions of dollars in healthcare savings.
Agentic AI: the new growth engine
One of the most significant shifts in 2026 is the emergence of agentic workflows as a major investment category. The concept is straightforward: instead of AI models that respond to individual prompts, agentic systems can plan, execute multi-step tasks, and interact with other systems autonomously.
This is not just a technical distinction. It changes the economics fundamentally. The shift from chatbots to agents mirrors the earlier transition from search engines to platforms. A search engine helps you find information. A platform lets you take action. Similarly, a chatbot answers questions, while an agent completes tasks. The market for task completion is orders of magnitude larger than the market for question answering. A single agentic system can replace multiple human workflows, which means the addressable market for AI expands from “tools that help people” to “systems that do work.” Companies building reliable agentic frameworks are attracting premium valuations because they are closer to delivering measurable ROI.
The challenge is trust. Enterprises will not deploy autonomous agents without robust safety guarantees, audit trails, and fallback mechanisms. The companies that solve the trust problem will capture the largest share of this emerging market.
The technical challenges are significant. Current large language models can hallucinate, make logical errors, and fail in unpredictable ways. When a chatbot gives a wrong answer, the user can simply ask again. When an agent takes a wrong action, the consequences can be real: incorrect financial transactions, damaged equipment, or compromised data. Building the guardrails that make agents reliable enough for enterprise deployment is the key engineering problem of 2026, and the companies closest to solving it are commanding the highest valuations in the agentic space.
Enterprise adoption reaches an inflection point
Virtually every major software vendor has integrated generative AI features into their platforms by mid-2026. Microsoft leads with Copilot across Office 365, Dynamics, and Azure, showing early evidence of monetization through premium pricing tiers. Salesforce’s Einstein GPT and various AI integrations across the Customer 360 platform have shown promising early adoption metrics.
But the real story is not the features. It is the pricing power. Companies that can demonstrate clear productivity gains are commanding premium prices for AI-enhanced products. The ones that cannot are watching customers treat AI features as nice-to-have rather than essential.
This divergence will accelerate. The pattern is familiar from previous technology waves. Early adoption is broad and undifferentiated. Everyone adds the new feature because it seems important. Then reality sets in, and the gap between implementations that deliver value and those that do not becomes impossible to ignore. The AI wave is following the same trajectory, just faster.
What makes this cycle different is the speed of iteration. Companies can test AI features, measure their impact on productivity and revenue, and make decisions about continuation in weeks rather than months. This means the winners and losers will be identified sooner, and the capital reallocation will happen faster. By the end of 2026, the gap between AI products that deliver measurable value and those that are just marketing will become obvious. The winners will consolidate their positions, and the pretenders will struggle.
One metric worth watching is the “AI premium” that companies can charge for products with AI features. Early data from enterprise software contracts shows that AI-enhanced products command a 15-25% price premium when they demonstrably improve productivity. But this premium evaporates quickly if the AI features do not deliver. Customer churn rates for AI products that fail to meet expectations are significantly higher than for traditional software, which means the cost of shipping a bad AI feature is higher than the cost of shipping no AI feature at all.
What this means for the next twelve months
The AI investment landscape in 2026 rewards selectivity over breadth. The days of throwing money at every AI startup are over. What matters now is:
- Energy and infrastructure: The bottleneck has moved from compute to power. Companies that can solve the energy problem for AI will attract significant capital.
- Agentic reliability: Building AI systems that can be trusted to operate autonomously is the next technical hurdle. Whoever cracks it wins a massive market.
- Enterprise monetization: The gap between AI features that generate revenue and those that do not will separate winners from losers.
- Regulatory navigation: As AI regulation tightens globally, companies that can demonstrate compliance and safety will have a structural advantage. The EU AI Act is already influencing how companies design their systems, and similar frameworks are emerging in Asia and North America.
The total AI market is projected to reach $300 billion in revenue by the end of 2026, according to multiple analyst estimates. But that top-line number masks enormous variation underneath. Some segments are growing at 50% or more annually. Others are already seeing margin compression as competition intensifies. The ability to distinguish between these segments is what separates successful investors from those who simply ride the wave and hope for the best.
The AI boom is not over. It is maturing. And maturity, while less exciting than the initial explosion, is where real value gets built.
Reader Dispatches
No reader responses yet. Share your technical perspective below.
Related Posts
The AI Margin Super-Cycle Has Begun: Why Software Investors Are Rewriting the Playbook
PitchBook's 2026 Advanced Software Launch Report declares the SaaS-pocalypse over and a new AI margin super-cycle underway. Here's what that means for software companies, investors, and the engineers building the tools.
AI Coding Tools' Security Flaws Hit 43%: What the Data Actually Shows
A study of 1.1 million Reddit posts reveals the most common security complaints about AI coding assistants, and it's not what you think.
AI's Carbon Problem Is Bigger Than Anyone Admits
Training a single AI model now emits more CO₂ than some countries produce in a year. Stanford's 2026 AI Index reveals the environmental cost of the compute arms race.